I. Yen-Carry Trade Unwinding?
The “yen‑carry trade” has been a key feature of global financial markets since roughly 2012. It rested on two pillars: ultra-low Japanese interest rates and either a weak or relatively stable yen. Hedge funds could borrow funds cheaply in yen, convert the proceeds to other currencies, and buy government bonds in those currencies. The beauty of this trade is that it increased downward
Today marked the conclusion of the September 15-16 FOMC meeting. The Fed's monetary policy committee delivered a widely anticipated 25bps increase in the federal funds rate (FFR), raising the target range to 3.75%-4.00%. Here are five key takeaways from today’s decision:
(1) The decision was unanimous. The FOMC voted 12-0 to raise the FFR by 25bps, showing unanimous agreement that tighter monetary policy is warranted. During his press conference today, Fed Chair Kevin Warsh said the vote “shows our resolve to achieve price stability on a timelier basis.” He pointed to three developments since July that brought the Committee together: stronger economic growth, insufficient improvement in inflation, and increased geopolitical risks. We reckon that the re-escalation of the war in the Middle East and the resulting prospect of more inflationary pressures from higher-for-longer oil prices was the deciding factor.
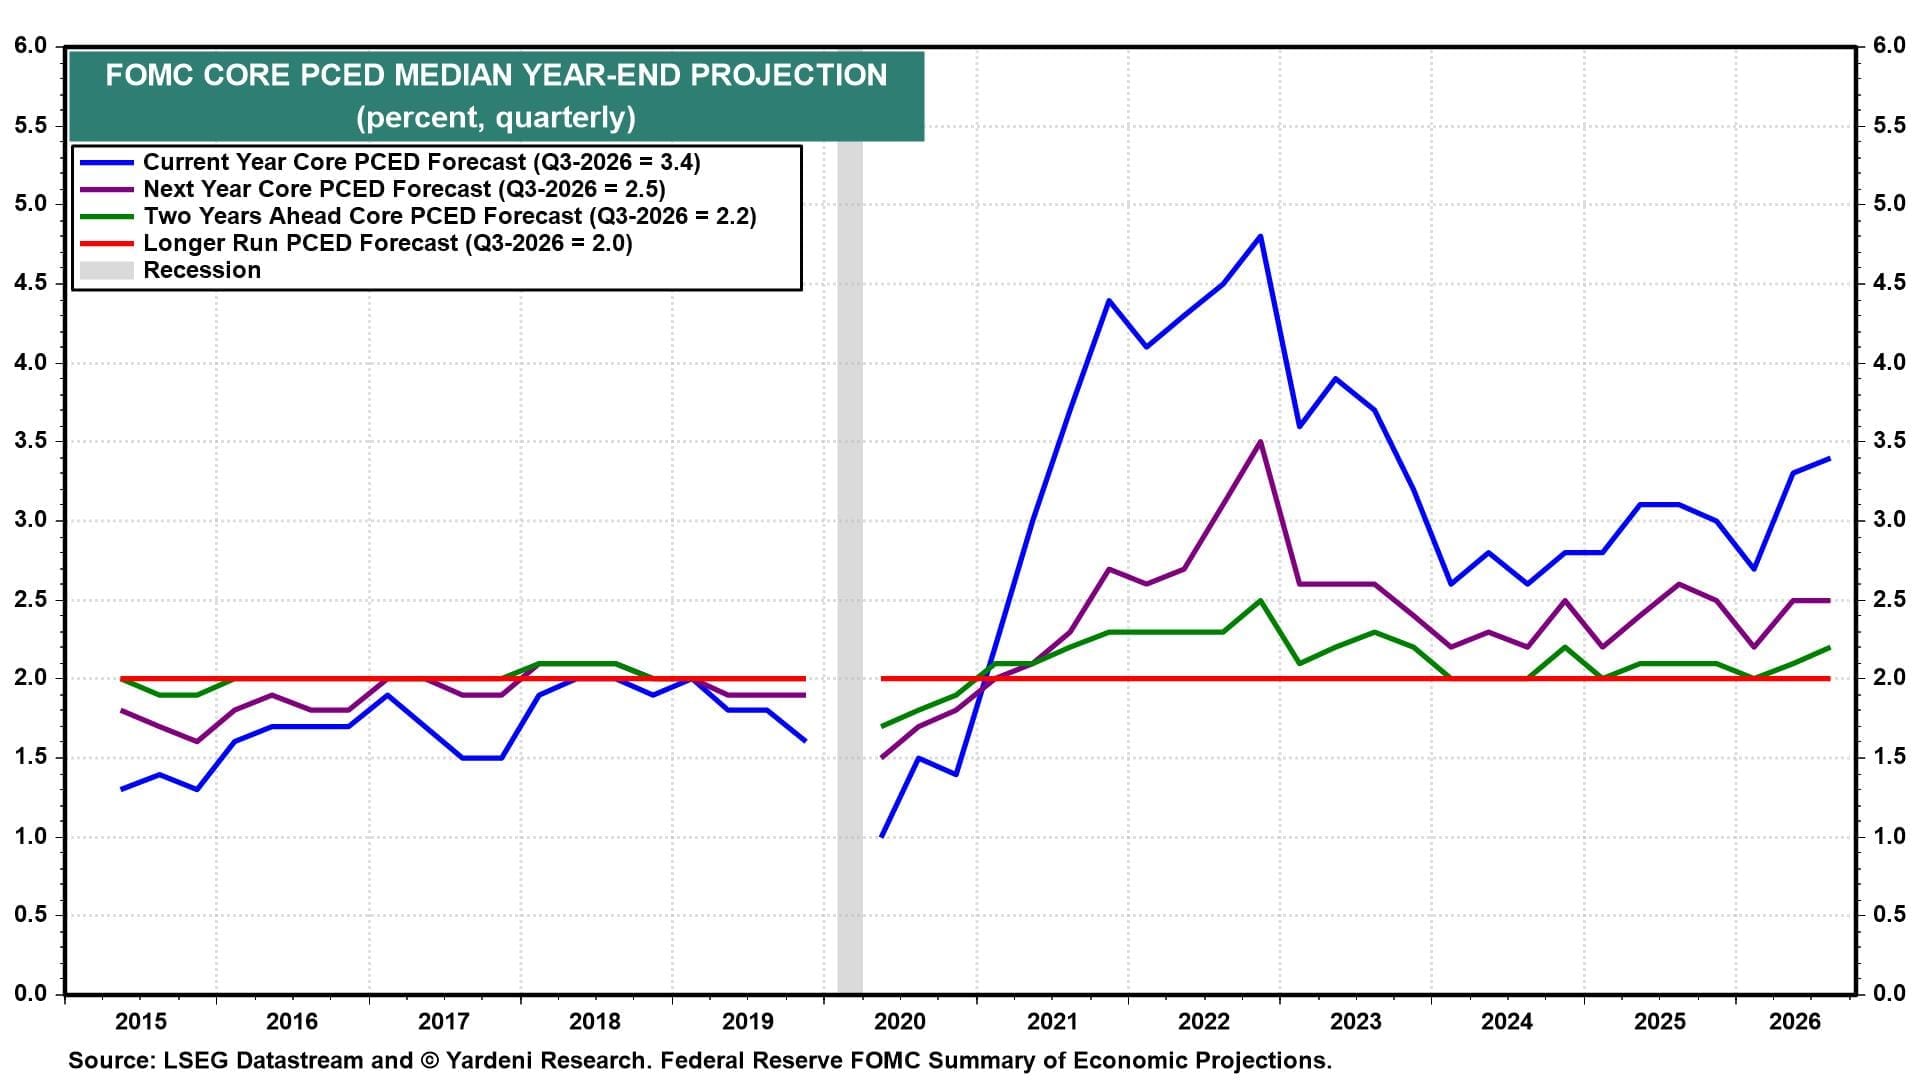
(2) Inflation remains the Fed’s predominant concern. Warsh said “inflation is too high and has been for too long” and that the Fed’s “predominant focus is on the price stability side of our mandate.” He added that this summer’s inflation readings “do not tell me that underlying trends have meaningfully improved,” with several key measures still running above 3.0% y/y. The Summary of Economic Projections (SEP) reinforced that message, with 2026 headline and core PCED forecasts revised slightly higher and inflation not forecast to return fully to the Fed’s target of 2.0% y/y until 2029 (chart).
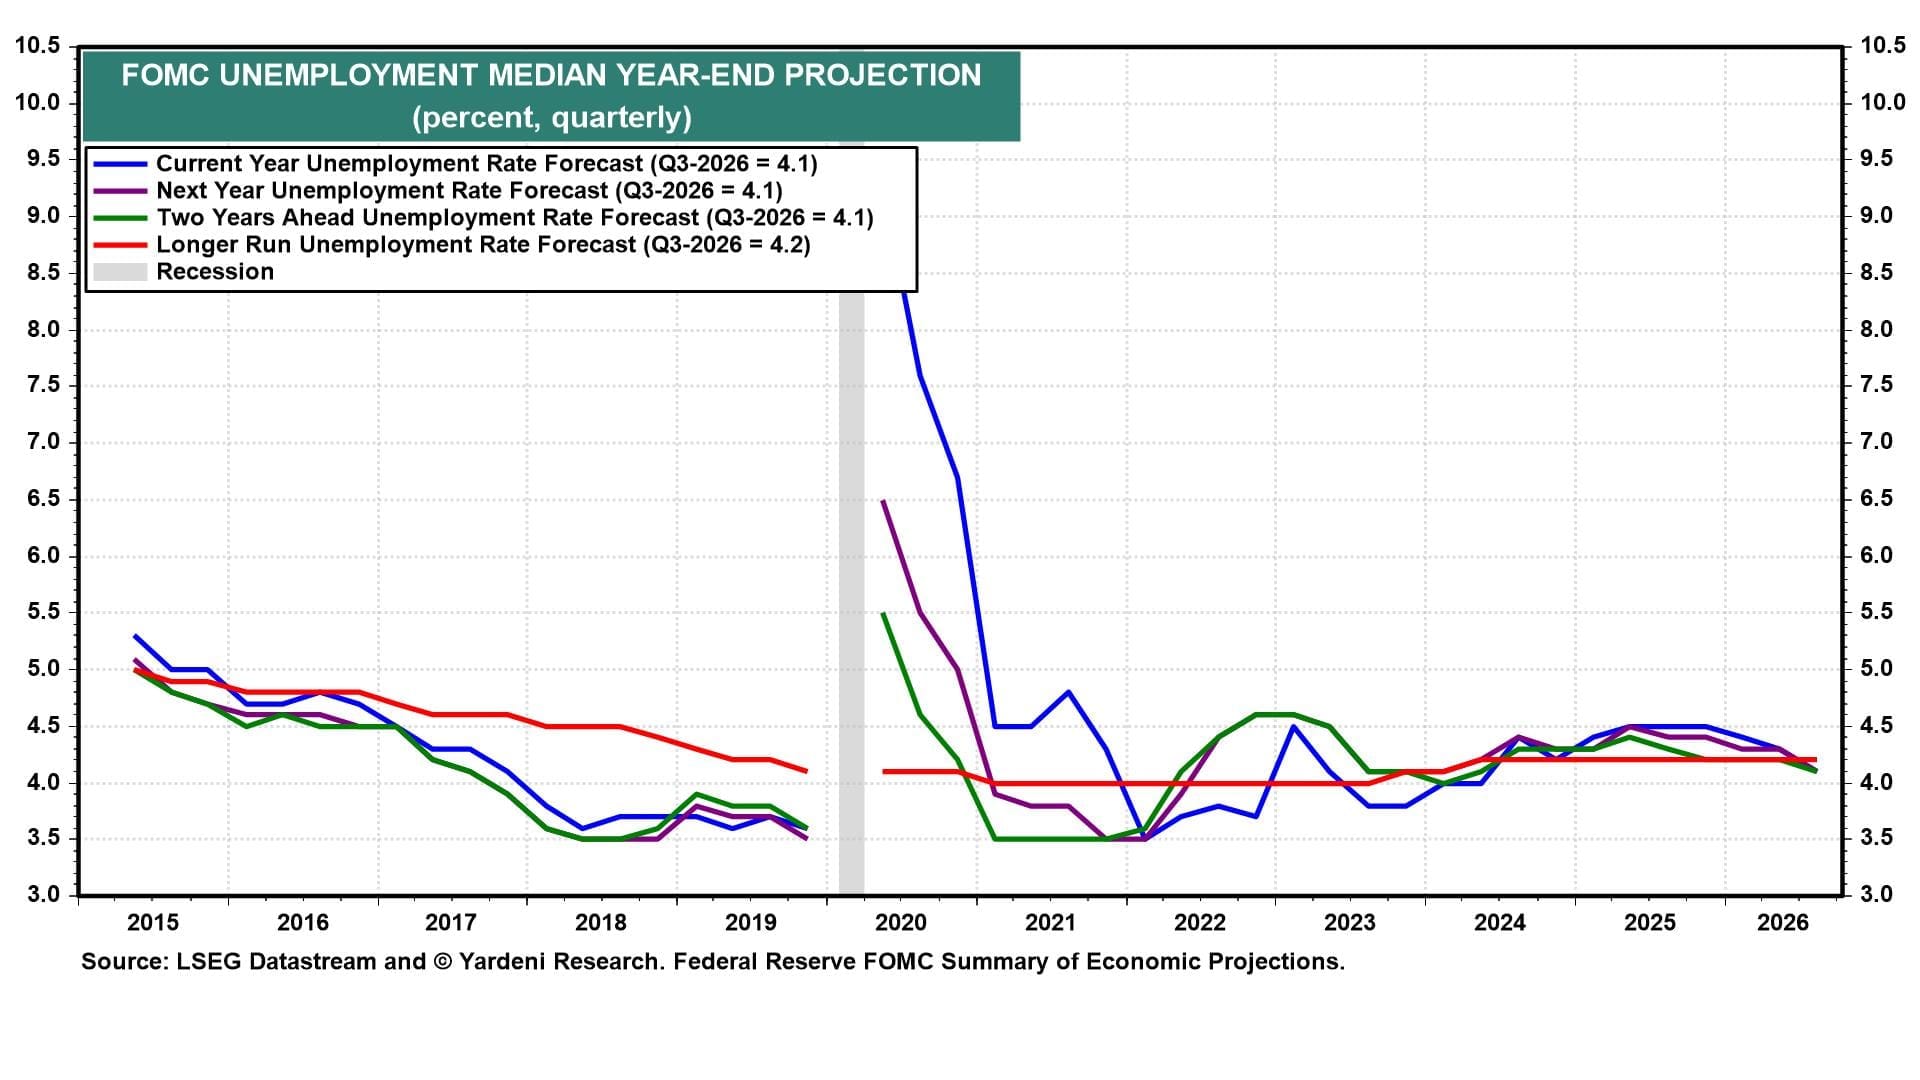
(3) The economy is stronger than the Fed thought in June. Warsh repeatedly emphasized that the “American economy appears to be strengthening,” pointing to improving hiring, private-sector earnings, business capital investment, and robust credit flows. He also said he would be “hard-pressed to describe broad financial conditions as restrictive,” a view widely shared across the Committee. The SEP similarly revised growth modestly higher and unemployment lower to 4.1% through 2028 (chart). Warsh also characterized the labor market as essentially at full employment, saying the “labor side of the Fed’s congressional remit is in good shape.” That gives the Fed more room to focus on the inflation side of its dual mandate.
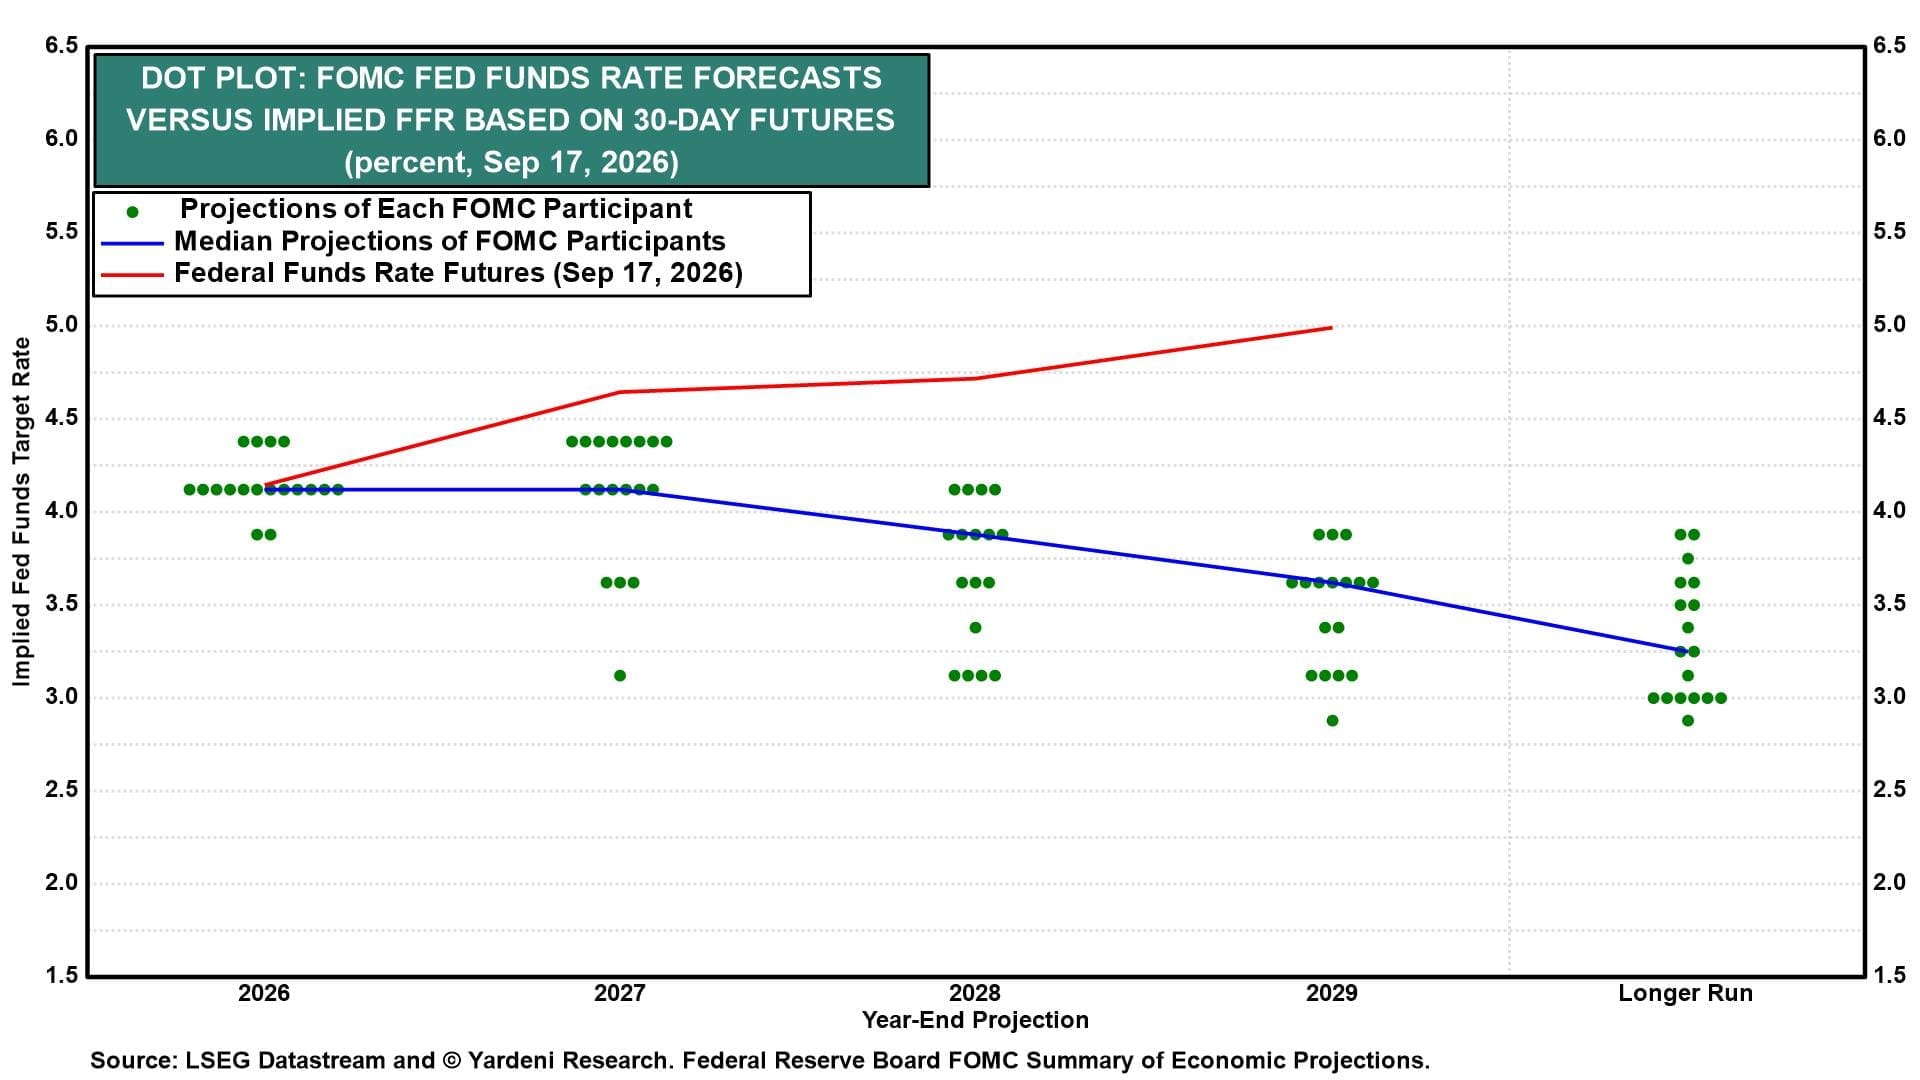
(4) The bar for another rate hike is low. The median of the 19 participants now expects another 25bps hike this year, no cuts in 2027, and only gradual easing thereafter, suggesting that today’s move was not intended as a one-and-done increase (chart). Four participants expect a third rate hike this year, while eight expect it in 2027.
Warsh refused to pre-commit, saying “I’m not in the forward guidance business,” but his reaction function was clear. Underlying inflation must move toward 2.0% “clearly and at sufficient speed,” and he said today that “this standard has not been satisfied.” He also stressed that the Committee had merely “removed a dose of accommodation” and remains “hard-pressed” to describe financial conditions as “restrictive.” Unless inflation moderates clearly, the case for another hike remains intact while economic growth is strong, the labor market is near full employment, and financial conditions are not restrictive.
II. US Economy
As the Fed delivered a hawkish rate hike, the latest economic data reinforced both the remarkable strength of the economy and the persistence of inflation. Here’s a look:
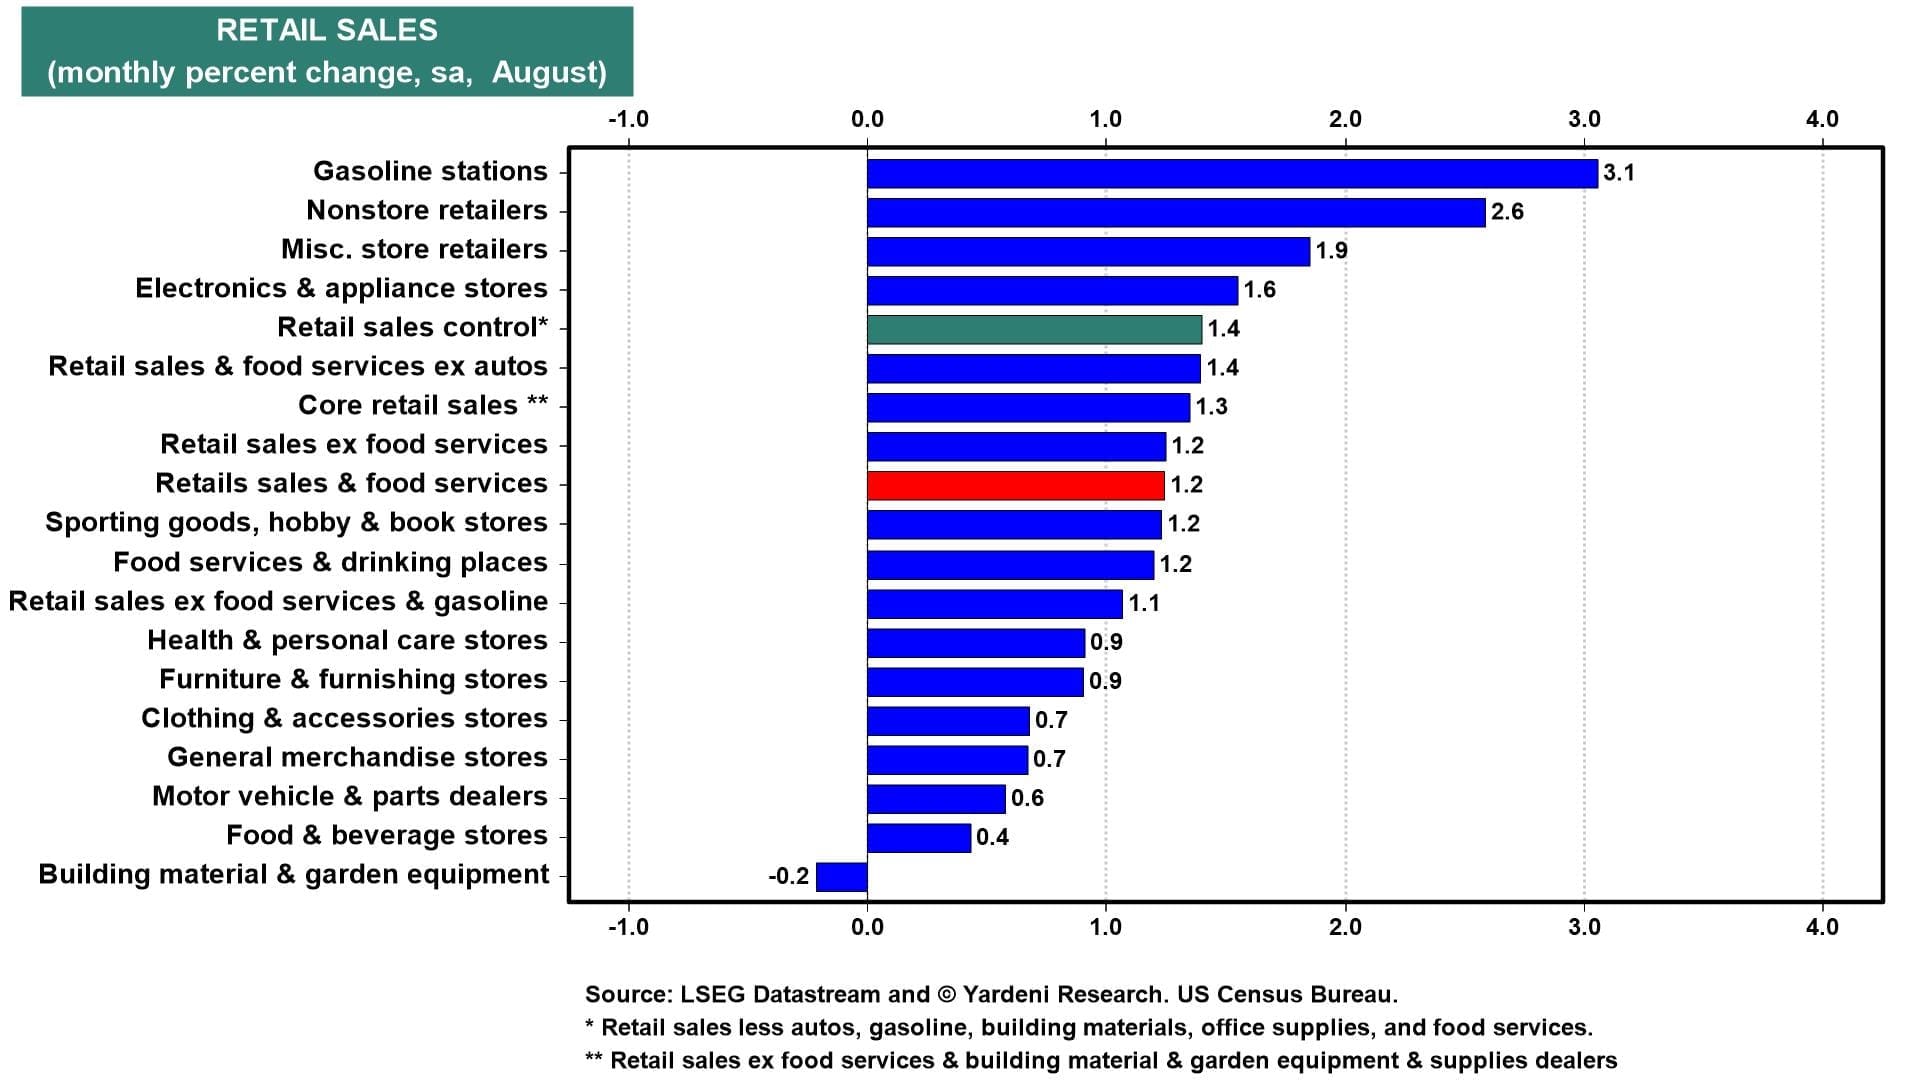
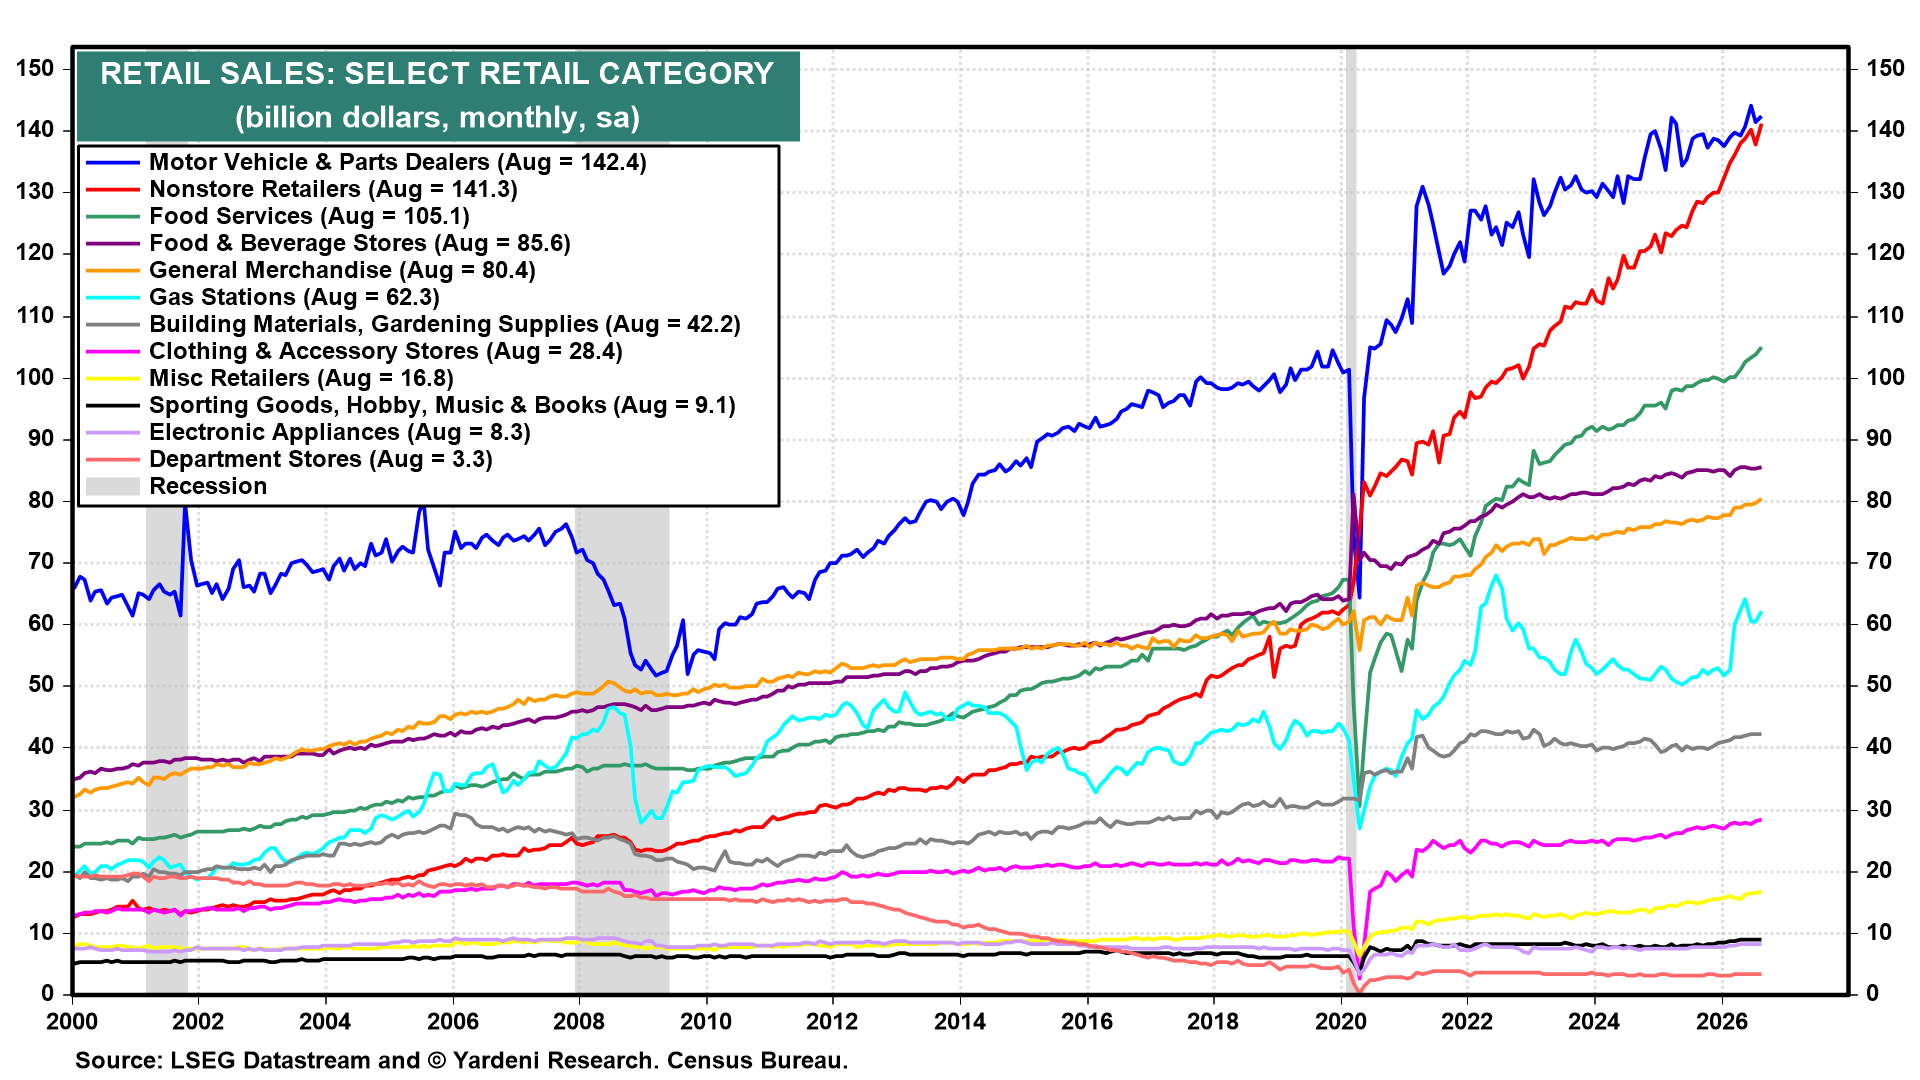
(1) Retail sales. August retail sales rose 1.2% m/m, above the 0.8% expected and the strongest gain since March 2026 (chart). Control-group sales, used in calculating GDP, surged 1.4% versus 0.5% expected. That was the strongest increase in nearly two years. The strength was broad-based, with 12 of 13 categories rising. Gasoline-station receipts jumped 3.1% as prices at the pump averaged about $4.06 per gallon in August, yet discretionary spending remained strong: food services & drinking places rose 1.2%, the most since May, while sporting goods also increased 1.2%.
Nonstore retail sales jumped 2.6% m/m to a record high (chart).
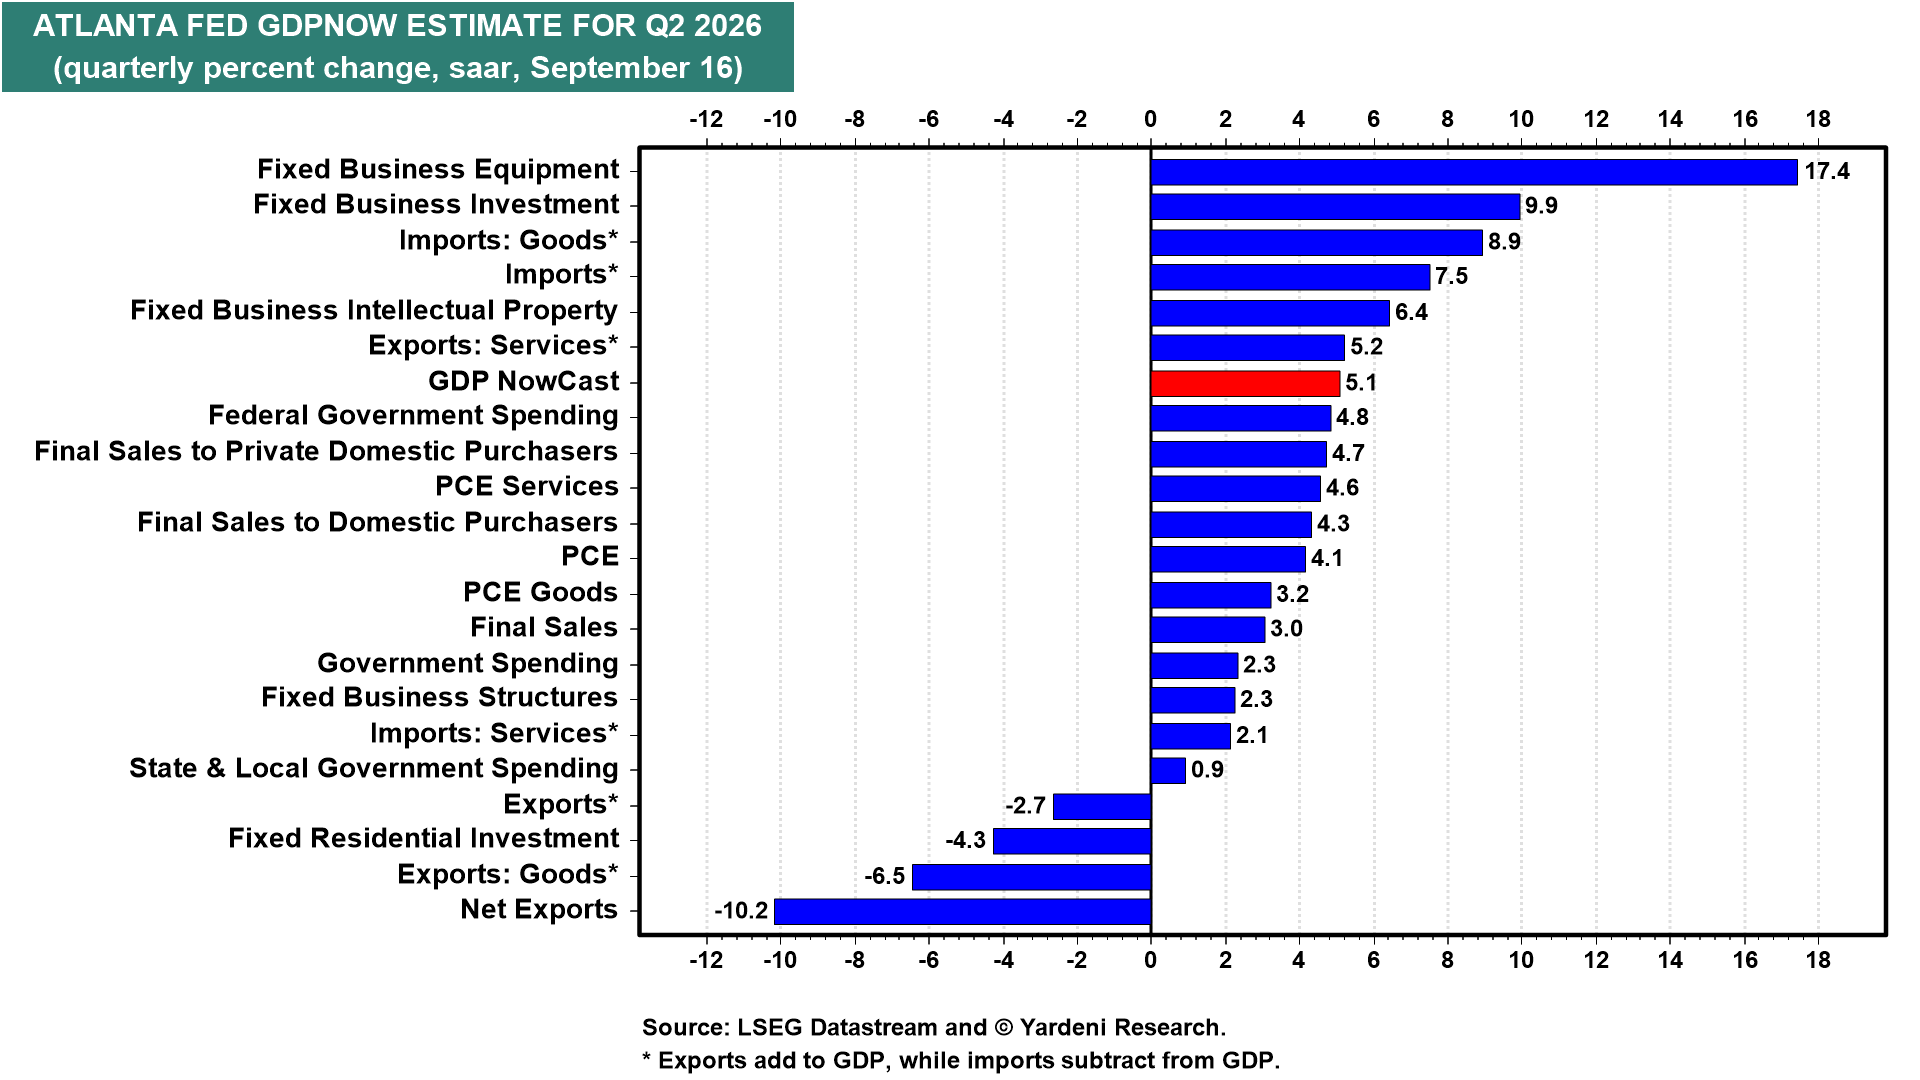
(2) GDP. The Atlanta Fed’s GDPNow tracking model revised its Q3 real GDP growth estimate up from 4.4% to 5.1% (saar). The upgrade was driven largely by stronger consumer spending, with real PCE growth now tracking at 4.1%, up from 3.6% (chart). That would mark the strongest quarterly increase in consumer spending since Q1-2023. Business spending also remains robust, reinforcing the picture of an economy supported by both resilient consumers and strong capital spending.
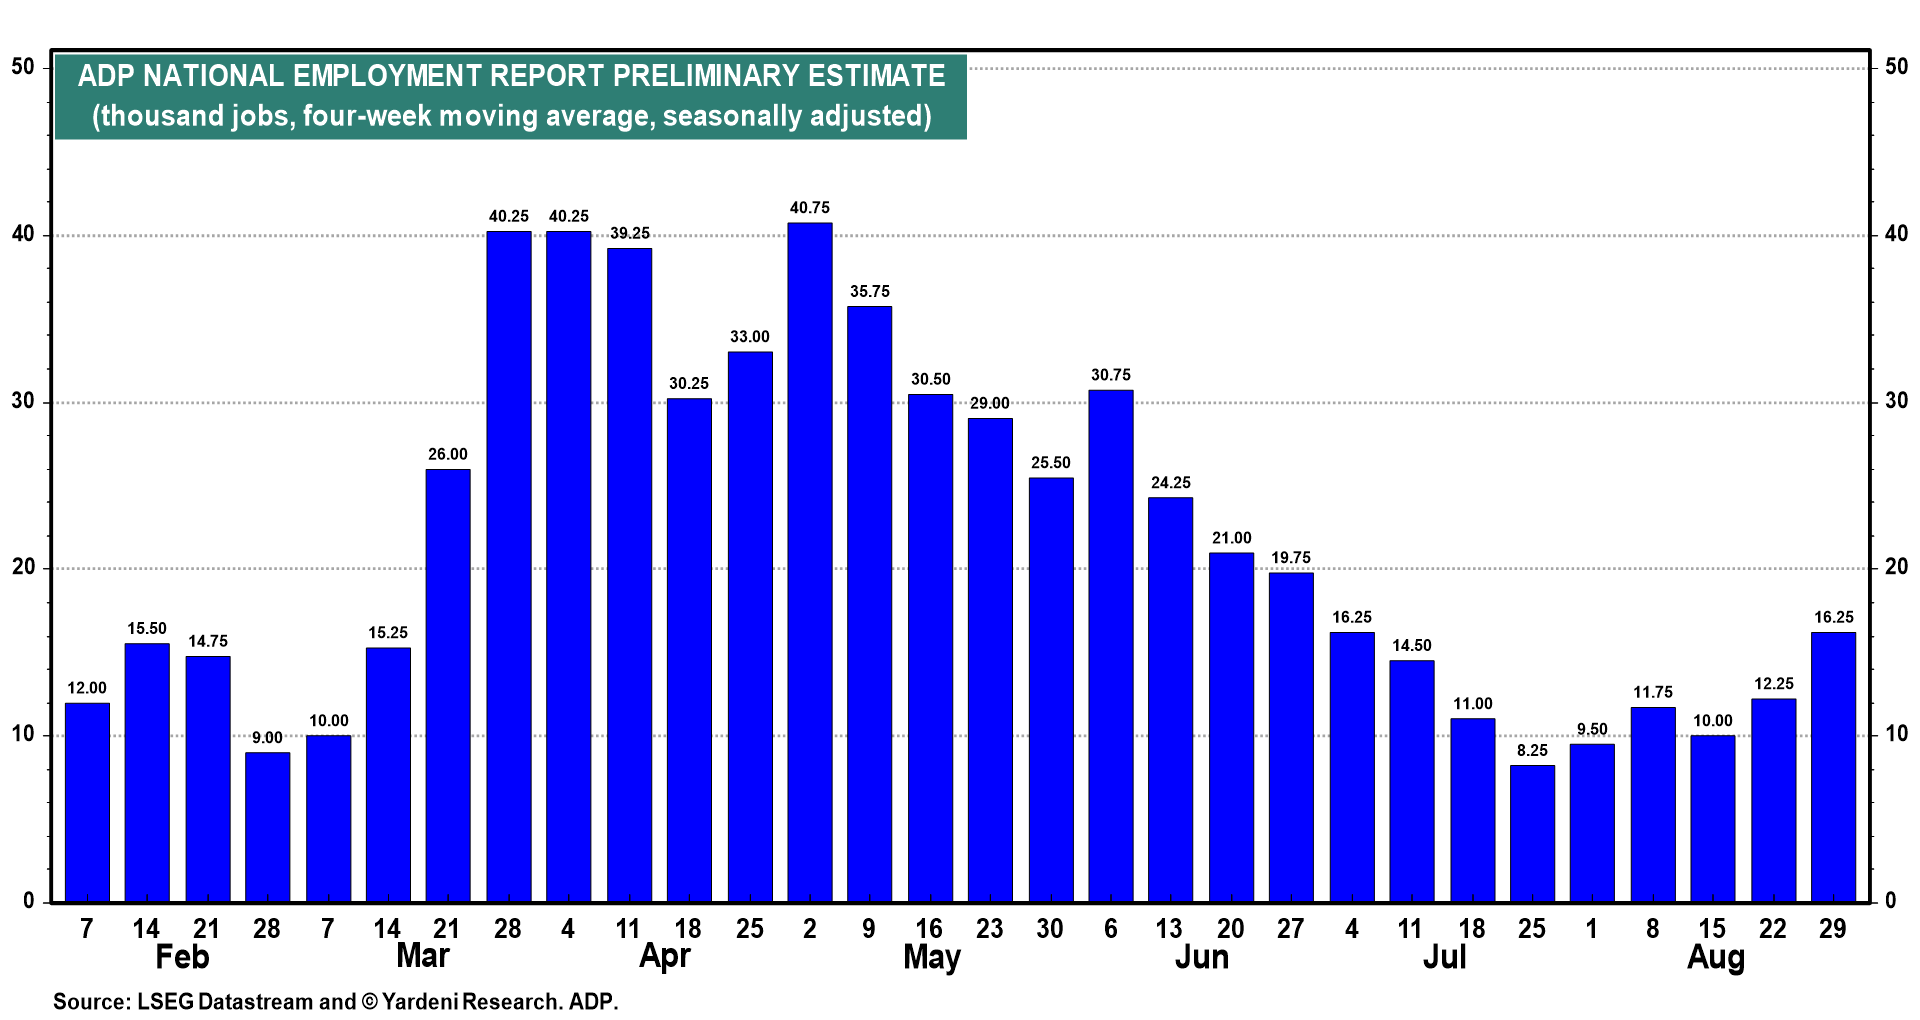
(3) ADP. A key reason for the resilience in consumer spending is the strength of the labor market. US private employers added an average of 16,250 jobs per week in the four weeks ending August 29, the most since early July (chart). That is consistent with a monthly pace of roughly 65,000 jobs, suggesting that the economy continues to operate at full employment.
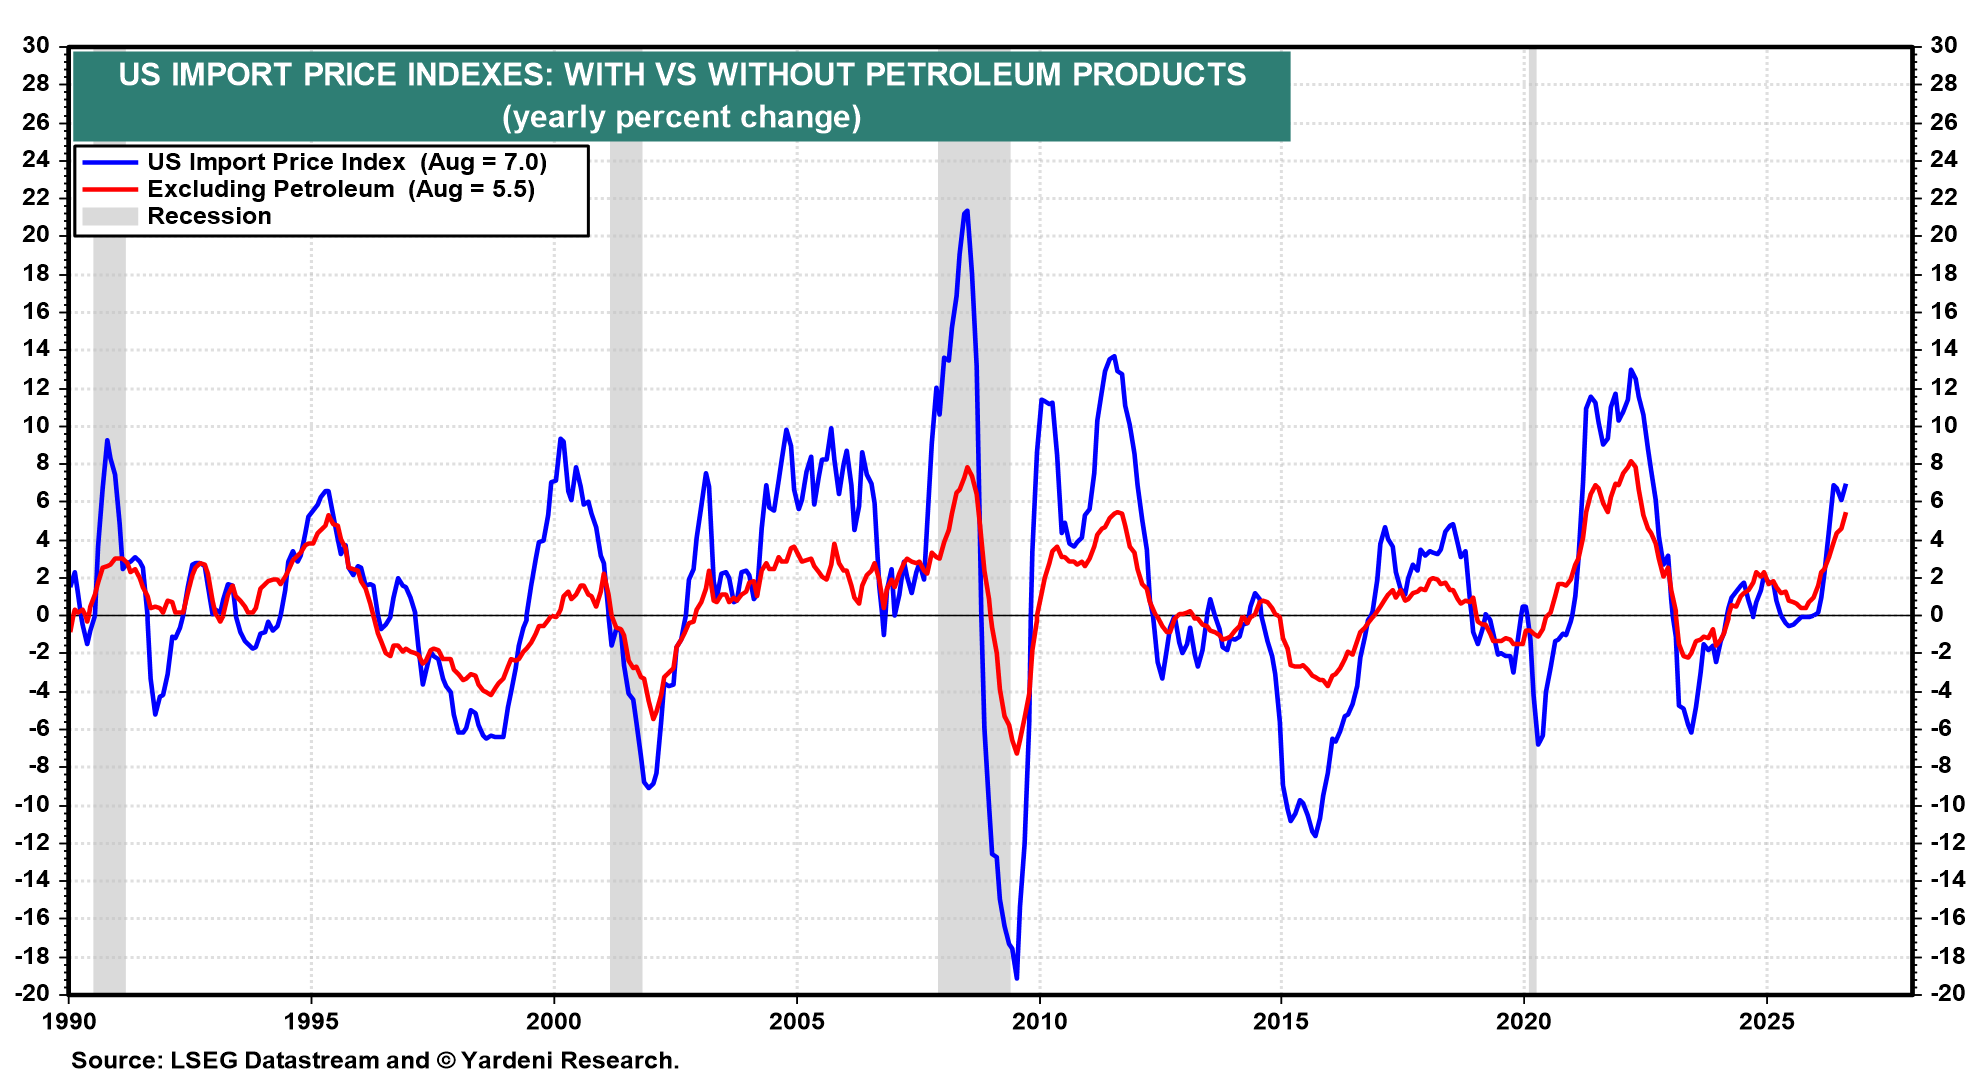
(4) Import prices. August'sdata on import prices point to persistent inflation pressures. The import price index rose 7.0% y/y in last month, the fastest pace since August 2022. Petroleum import prices rose 27.3%. But even excluding petroleum, import prices rose 5.5%, the highest increase since May 2022 (chart).
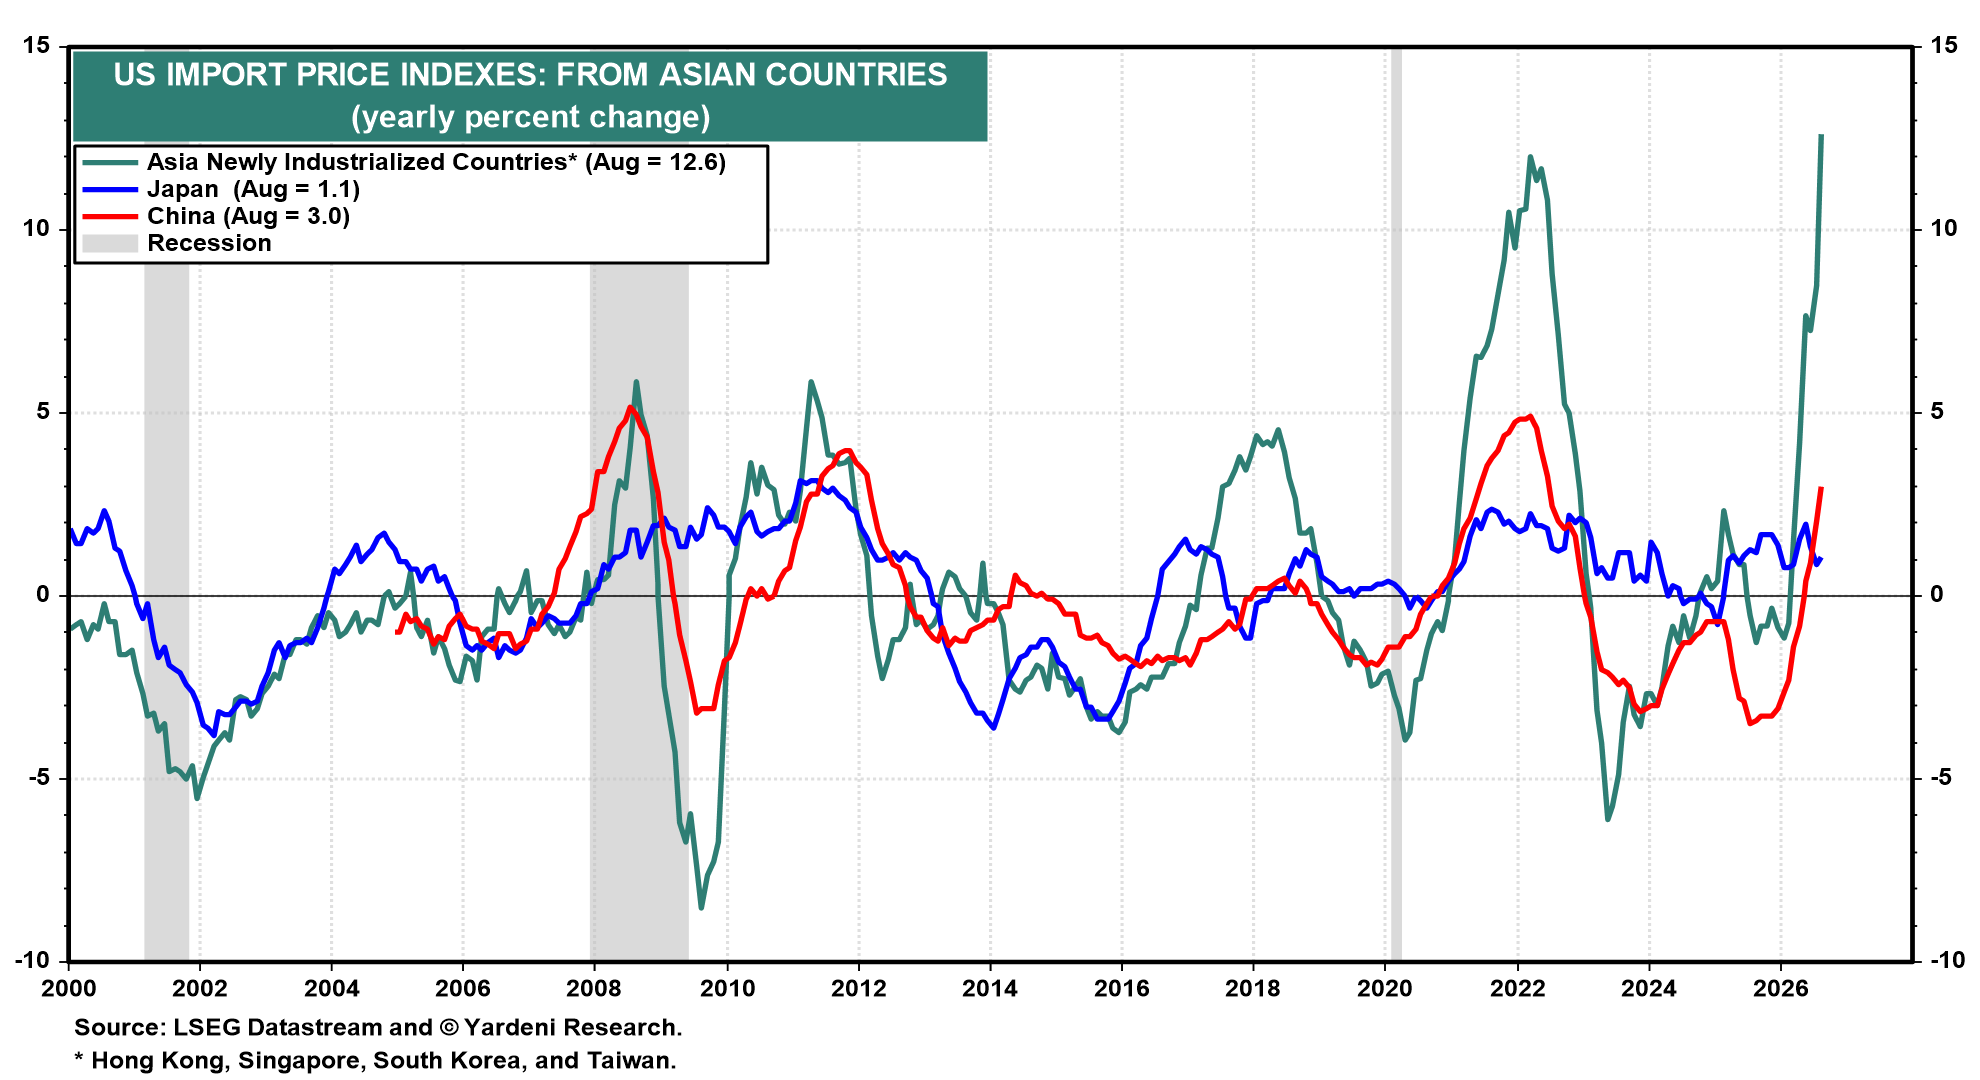
Import prices from the newly industrialized Asian countries surged 12.6% y/y in August, reflecting AI-related demand for semiconductors, servers, memory, and other electronics outstripping supply (chart). That suggests the AI buildout will remain inflationary for now, before AI brings the fruits of disinflationary productivity growth.
💡
Join the discussion with Ed below! To leave comments or questions, log in to the Yardeni QuickTakes website and post them at the end of the QuickTakes article. Paid members' contributions may be featured in our segment, "Ed Answers Your Questions".
We’re still strong believers in our Roaring 2020s scenario, hinging on a productivity boom that strengthens economic growth even as it contains inflation. However, we’ve shaved the subjective odds that we ascribe to that scenario from 80% to 70% and now see a 30% chance that rising geopolitical and other risks could derail it. Today, Ed and Elias update our deepened worry list, detailing the concerning prospects, as well as reiterate the reasons that we remain bullish. We
Ed Yardeni has been calling markets since the early 1980s — as chief investment strategist at
Deutsche Bank and Prudential, and before that as an economist at the Federal Reserve Bank of
New York — before founding Yardeni Research. Yale PhD. Author of seven books, including
Predicting the Markets, all free to members.
Seven books · free to members
Every call Ed makes, as he makes it.
✓5–8 full posts every week
✓Wednesday webcast — two days before public
✓The full archive & chart library, with saved charts
✓Ask Ed — your questions, answered in a Q&A post every week or two